About $36.8 billion a year in federal transportation money disappears Oct. 1. When funding gets tight, the questions about what got built get harder, and the projects with a clean record, from the model to the pour, will be the ones with answers.
The Wall Street Journal catalogued the shortcuts driving the data center boom. Here is what they mean if you are the one wiring the building.

A lot of money is going into building data centers faster. The Wall Street Journal on Sept. 1 catalogued six of the techniques doing it, with reported time savings running from a few hours to six months.

Bloomberg, using data from the market research firm Sightline Climate, reported that of roughly 12 gigawatts of U.S. data center capacity slated for 2026, only about a third was really under construction. The reasons cited: shortages of transformers, switchgear and batteries.

Plenty of people have strong opinions about the buildout. Set those aside. The work is being bid and built right now, and it asks something different of the trades than the work before it.

What are the six techniques speeding up data center construction?

Six unrelated products from six unrelated companies. Read them as a group and one strategy shows up. Speed is not coming from anyone working faster on site. It comes from decisions moved upstream, out of the field and into a shop or a spec.

Three land directly in electrical scope.

The drilling robot. DEWALT and August Robotics launched it this year reporting 99.97% accuracy across more than 90,000 holes. It drills anchors for server rack stops and the structural legs carrying overhead MEP. That robot sets the geometry your hangers land on.

The connectors. 3M’s expanded beam technology cuts plug-up from roughly three minutes per connector to as little as 30 seconds, across hundreds of thousands of them. Connection speed stops mattering if you connected the wrong thing quickly.

The factory-built rooms. The big one. Rooms get assembled in a plant, trucked in and set. Your coordination package is no longer a guide for a crew. It is an input to a production line.

Every shortcut there buys schedule certainty by giving up flexibility, and flexibility is what the field has always used to make imperfect drawings work. None of that hurts when the information is right. All of it hurts when the information is wrong, because the correction that used to happen on a Tuesday afternoon now happens on a truck.

How much of a data center’s cost is electrical work?

Data centers are not big office buildings with more outlets. On this work the electrical scope has moved from a supporting line on the cost sheet toward the center of it, which changes who carries the risk when something goes wrong and how much leverage the trade has at the table.

On an AI data center, electrical is the biggest line on the cost sheet. Turner & Townsend’s 2025 data center cost index puts electrical systems at 48% to 54% of construction cost, ahead of mechanical, and several times the shell. The inputs are getting more expensive, too: copper wire is up 17.9% from a year ago.

The International Brotherhood of Electrical Workers estimates 45% to 70% of the construction budget goes to the electrical subcontractor. That covers the sub’s full scope rather than one line on a cost sheet, and the union publishes it without showing its math. Still, a cost consultant and the electricians’ union, measuring different things, land in the same place: roughly half the job.

Electrical and power share of construction cost

Project typeElectrical/power shareSource
Typical commercial building15% – 20%Industry baseline
AI data center (2018)28% – 32%CBRE, JLL cost-stack analyses
AI data center (current)35% – 45%CBRE, JLL cost-stack analyses
AI data center, full electrical sub scope45% – 70%IBEW estimate

The IBEW figure measures the electrical subcontractor’s entire scope rather than a single line on a cost sheet, which is why it sits well above the CBRE and JLL numbers.

Why can’t electrical mistakes get fixed in the field on these jobs?

On most work, rework is a cost line. Somebody eats it and the job moves. On this work that tolerance is mostly gone, and the reason has less to do with craftsmanship than with what the building does once it is energized.

Chris Doyle has been in the trade since 1988 and works as a detail manager at Redwood Electric on an active data center project in Reno, Nev. The work has not only grown in volume, he said. It has raised the technical floor, “from single lines to ladder logic and the understanding of how these systems are supposed to work.” Not only for the people running jobs. “That’s the people that are building it.”

“At the end of the day, if there’s any mistakes in a UPS system, you’re talking about millions of dollars in downtime. The bar is very, very high, not just because we as an institution here want it to be, but because that’s what the industry demands.”

Most rework was never a field execution problem to begin with.

  • A Construction Industry Institute study of industrial projects found design changes, errors and omissions drove 79% of the cost of quality deviations. Construction deviations drove 17%.
  • A 2018 FMI and PlanGrid survey traced 48% of U.S. rework to poor project data and miscommunication, about $31.3 billion that year.

The field has spent decades absorbing mistakes made upstream. Prefab takes that away. The errors don’t stop. The shock absorber does.

The standards are still catching up. IEEE authorized Project P3710 in June 2025 to write design guidance for modular data centers, and it is still in development. The NEC and UL frameworks everybody works under were written for equipment installed in place, not built in a plant and shipped.

We have written before about what a 40-minute drawing hunt costs and why projects run late for reasons that have nothing to do with weather.

What’s really slowing down data center construction?

The six techniques all attack labor hours on site. Neither of the two things ultimately gating these projects lives there. Equipment and qualified people are procurement problems, not productivity problems, and no amount of speed in the field moves either one. Both get decided long before a crew mobilizes.

Gear. Wood Mackenzie’s Q2 2025 survey put power transformers at 128 weeks and switchgear around 44. Its 2026 read, reported by Data Center Knowledge, has substation transformers past 160 weeks, up from roughly 140 in 2023.

Electrical equipment lead times

EquipmentLead timeAs ofSource
Power transformers128 weeksQ2 2025Wood Mackenzie
Switchgear~44 weeksQ2 2025Wood Mackenzie
Substation transformers~140 weeks2023Wood Mackenzie via Data Center Knowledge
Substation transformers160+ weeks2026Wood Mackenzie via Data Center Knowledge

Wood Mackenzie’s most recent per-equipment survey is from Q2 2025. Its 2026 substation transformer figure was reported by Data Center Knowledge.

Lead times are cyclical and will come down. Distribution transformers already have, falling from more than 100 weeks in 2023 to about 30. Schneider Electric announced in March 2025 it will invest more than $700 million in U.S. operations through 2027, including switchgear and medium-voltage production. Shorter lead times still do nothing to restore the ability to adjust a prefabricated room after it comes off the truck. The shortage is a cycle. Front-loaded risk is a change in how the work gets built.

People. Google’s May 2025 white paper “Powering a New Era of American Innovation” reports that nearly 10,000 American electricians retire or change careers each year against about 7,000 new entrants.

The Bureau of Labor Statistics counted 818,700 electricians in the U.S. in 2024, projects 9% employment growth through 2034 and expects about 81,000 openings a year.

Watch what the companies with the most riding on these things are doing about it. Google.org funded the electrical training ALLIANCE, the joint IBEW-NECA apprenticeship organization, targeting 100,000 electrical workers and 30,000 apprentices. Siemens set a goal of bringing 200,000 electricians and manufacturing experts into the workforce by 2030.

One company doing that is a press release; two is a signal about which input is hardest to source. The money is going to apprentices, not another robot.

What should electrical contractors change to win this work?

The answer to industrialization is not working faster. Rather, it is refusing to rebuild the same thinking on every job while everything around you gets standardized. The firms that will hold margin here are the ones treating their own process as an asset with a version number, not something reassembled from memory each time.

Doyle argues data centers are more alike than most projects. “There’s an execution that can be about 80% the same,” he said. “So we shouldn’t have to start at zero like most projects tend to.”

The industry is moving his way. The Open Compute Project is building standardized reference designs for AI data centers, and Google contributed the first one, a facility design built around its TPU systems. But OCP’s own leadership describes the first wave of AI data centers as siloed, built with little coordination between vendors. The repeatable share runs high inside one customer’s program and lower across customers.

That tells you where to aim. The roughly 20% that does not repeat is where the job is won or lost, and the only way to have capacity left for it is to stop re-solving the 80%.

For an electrical sub, four habits:

  • Build tool sets once and reuse them, so takeoffs start from your standard, not from scratch.
  • Verify before release, not on arrival. Anything headed to a fab shop gets checked while changing it is free.
  • Treat submittals and RFIs as schedule work, not paperwork handled between other things.
  • Catch the conflict in design review while it is still a markup, because the field can no longer catch it for you.

The part that can’t be prefabricated

The pouring, the coating, the drilling, the connecting, all of it is getting faster and further from the hands that used to do it. The judgment that has to happen before any of it starts has not moved.

Somebody still has to know the drawing is wrong: that the anchor pattern doesn’t match the rack layout; that the routing won’t clear the structure; that the gear on the submittal isn’t the gear on the plan.

That work is getting more valuable, not less. The trades who do it consistently and can prove it get the calls.

Frequently asked questions

What percentage of data center construction cost is electrical work?

Turner & Townsend’s 2025 data center cost index puts electrical systems at 48% to 54% of construction cost, the largest single category. The IBEW estimates 45% to 70% measured as the electrical subcontractor’s full scope. Both figures exclude servers and IT equipment, which make electrical a much smaller share of total project cost.

How long are transformer and switchgear lead times in 2026?

Substation transformer lead times passed 160 weeks in 2026, up from roughly 140 weeks in 2023, according to Wood Mackenzie as reported by Data Center Knowledge. Wood Mackenzie’s most recent per-equipment survey, from Q2 2025, put power transformers at 128 weeks and switchgear at about 44.

Why is prefabrication riskier for electrical contractors on data center projects?

Factory-built assemblies lock decisions in before the crew arrives, so a drawing error the field once fixed with a Tuesday afternoon adjustment has to be caught before the assembly ships. That matters because most rework starts upstream: research from the Construction Industry Institute and from FMI traces it largely to design errors, changes and poor project data rather than field execution.

Is there a shortage of electricians for data center construction?

The Bureau of Labor Statistics counted 818,700 electricians in 2024 and projects about 81,000 openings a year through 2034, many from retirements and career changes. Google.org is funding an IBEW-NECA effort to train 100,000 electrical workers and 30,000 apprentices, and Siemens set a goal of adding 200,000 electricians and manufacturing experts by 2030.

Bluebeam builds software for specialty contractors, MEP trades and energy and infrastructure teams. See how AI-assisted drawing review changes what gets caught before the truck shows up.
Catch the conflict while it’s still a markup.

The hidden price tag on familiar workflows — and why the math is getting harder to ignore.

Picture a superintendent on a commercial job, 10 weeks from substantial completion. They’re not behind on approvals or missing a deadline. They’re looking for a drawing.

Not a drawing that doesn’t exist. A drawing that does exist, somewhere, in one of four shared drives their team has accumulated across three years of project turnover. They find it 40 minutes later. It’s version 7, and they needed version 9.

Nobody budgeted for that 40 minutes. Nobody budgeted for the calls that followed, or the rework that came after. That’s the thing about document management failures: they don’t present as failures. They look like Tuesday.

The construction industry has built an entire operating culture around workflows that feel good enough — until you calculate what good enough is costing you. Bluebeam works with more than 4 million construction professionals worldwide, and this pattern shows up everywhere: in the data, on the jobsite, and in the stories crews tell about the moment they finally changed how their teams work.

Those patterns are confirmed by Bluebeam’s own research. The AEC Technology Outlook 2026, a global survey of more than 1,000 construction professionals published in October 2025, found that only 11% of AEC firms are fully digital across all project phases. The other 89% are still relying on paper, spreadsheets and legacy tools — especially in the field and during closeout, where document integrity matters most.

This piece makes the case for why that gap matters — in dollars.

Bluebeam’s Document Management for Construction 2026 Guide goes deep on what a modern document workflow looks like. What follows is the business case for why it matters.

The Gap Between ‘Digital’ and Actually Digital

Every firm in construction will tell you they’ve gone digital. In a narrow sense, most of them have. PDFs replaced paper; email replaced fax; shared drives replaced filing cabinets. That counts.

Still, digital tools and digital workflows are not the same thing. Nearly half of AEC professionals still rely on paper during design or handover, according to the AEC Technology Outlook 2026. Nearly 40% report challenges managing collaboration across the full project lifecycle, especially when crews are siloed between design, construction and operations. Meanwhile, 23% cite integration complexity as their top barrier to adoption — higher than cost, higher than time, higher than lack of leadership buy-in.

That partial digitization is exactly where the cost hides. The filing cabinet is gone, but the chaos it represented hasn’t been. It’s been distributed across inboxes, cloud folders, and markup files with names like “final_FINAL_v3_revised.pdf.” Field teams are hunting for information across systems that don’t talk to each other, and that hunt shows up on the job as wasted time, cost overruns and risk.

The tools are there. The connection between them often isn’t.

What 14 Hours a Week Costs

The most detailed look at where construction crews spend their time comes from the FMI and PlanGrid “Construction Disconnected” study, a 2018 survey of nearly 600 construction leaders. The finding that should stop any PM cold: construction professionals spend 35% of their time — more than 14 hours a week — on what the study called “non-optimal” activities. Hunting for project data; resolving conflicts; dealing with rework. In other words, not building or managing. Looking.

The breakdown is worth sitting with. Of those 14-plus hours, 5.5 go to chasing down project information. Another 4.7 go to conflict resolution. The remaining 3.9 go to mistakes and rework. Across the US construction workforce, that wasted time carries an estimated annual labor cost of $177.5 billion.

That figure is specific, to be sure, to 2018 dollars and one methodology. Yet the directional argument holds regardless: when your most experienced people are spending a third of their week chasing information rather than making decisions, you’re paying a tax on every hour you’ve hired them. That tax doesn’t show up on any job cost report.

Rework, RFIs and the Paper Trail Nobody Wanted

The time loss is real. Yet it’s the downstream consequences that turn an efficiency problem into a business problem.

Start with rework. The Construction Industry Institute’s field rework research, drawn from a database of 144 industrial projects, established the benchmark the industry still cites: direct rework costs run about 5% of total construction cost. That figure understates the actual hit because rework is systematically underreported — roughly a third of the project teams CII surveyed believed their recorded rework captured only 50% to 75% of what occurred.

What’s more, the 2018 FMI and PlanGrid study put a dollar figure on it: $65 billion of US construction spending goes to rework annually, and $31.3 billion of that — 48% — traces back to poor communication and bad project data. Not bad workmanship. Bad information.

The broader picture is starker. A 2021 Autodesk and FMI study estimated that inaccurate, incomplete or inaccessible project data cost the global construction industry $1.85 trillion in 2020, driving $88.69 billion in rework alone. Thirty percent of respondents said more than half of their project data was “bad” in some way — inaccurate, outdated, inaccessible or entered twice.

Then there are RFIs. A Navigant Construction Forum analysis of roughly 1.1 million RFIs across 1,362 projects found that the average project in the sample generated 796 RFIs, each costing an estimated $1,080 to review and respond to. That works out to about $860,000 per project in RFI processing alone.

The median response time in the analysis, meanwhile, was 9.7 days. And roughly 22% of RFIs never got a response at all — a rate Navigant called a leading indicator of deeper trouble, from an overwhelmed response system to no real controls over how RFIs get processed in the first place.

Change orders add another layer. An AIA analysis of nearly 900,000 change orders across more than 18,000 completed US building projects found that change orders average 4% to 5% of contract value, with the top of the typical range running about 15%.

More useful than the average, though, is the timing: most change orders land in the back half of a project, and AIA found that the later one arrives, the fewer options an owner has and the more it tends to cost.

This is another way of saying the expensive changes are the ones nobody saw coming — because the information that would have surfaced them was sitting somewhere no one could reach.

None of these, to be clear, are acts of God. They’re what happens when crews on the same job are working from different versions of the same information.

The Productivity Gap That Makes It Worse

The document management problem doesn’t exist in isolation, either. It sits inside a broader productivity problem that construction has been living with for decades.

McKinsey Global Institute’s 2017 analysis found that global construction labor productivity had grown only 1% per year over two decades, compared to 2.8% for the total world economy and 3.6% for manufacturing. In the US, construction labor productivity is lower today than it was in 1968.

A 2023 McKinsey update found that construction productivity improved only 10% between 2000 and 2022 — while the broader economy improved 50% and manufacturing improved 90% over the same period.

That stagnation has many causes, and document management is one of them. When nearly a third of a crew’s week goes to finding and reconciling information, no technology investment fully compensates for it. The workflow has to change.

Bluebeam’s Document Management for Construction 2026 Guide lays out what that change looks like in practice — from version control protocols to real-time collaboration workflows to closeout documentation that doesn’t require a four-month archaeological dig.

Why the Math Is More Urgent Now

The inefficiency was always there. What’s changed is the margin available to absorb it.

GC net margins sit around 5%-6% in a good year, and about one in six contractors say they’ve absorbed recent cost increases themselves rather than pass them through — a strategy that works until it doesn’t.

Meanwhile, construction wages rose 4.2% year over year as of August 2025, and Associated Builders and Contractors estimated the industry needed to attract 439,000 workers in 2025 alone — a number it raised to 499,000 for 2026.

Effective tariff rates, moreover, on construction goods hit a 40-year high of 25% to 30% in 2025, according to Deloitte’s 2026 Engineering and Construction Industry Outlook. AGC’s producer price data shows what that did downstream: aluminum mill shapes up 30.5% across 2025 and steel mill products up 17%, the steepest increases since 2022. Total US construction spending, meanwhile, was down almost 3% year over year by July.

When every cost input is moving the wrong way at once, self-inflicted costs start to matter in ways they didn’t when margins were thicker. Rework that was a nuisance at 12% margin can be existential at 5%. RFI delays that were an annoyance on a fully staffed project become critical path issues when you’re already shorthanded.

There’s a workforce dimension, too.

The AEC Technology Outlook 2026 found that 44% of firms say advanced technology plays a key role in attracting and retaining workers, alongside culture and pay. In an industry already facing a serious labor shortage, document chaos isn’t just an efficiency problem; it’s a recruiting problem. Younger workers notice when they’re handed outdated systems on day one.

The firms absorbing these costs without fixing the underlying workflow aren’t just losing money on individual jobs. They’re building structural disadvantages into how they operate.

What Good Looks Like

The answer isn’t another tool, but a different way of working. The firms that have made the change are producing results that show up on the bottom line.

Consider DPR Construction’s experience on the Alta Bates Summit Medical Center project in Oakland. Facing a 31-day schedule delay and an accelerated rebar fabrication timeline, DPR turned to Bluebeam Studio Sessions to run simultaneous, real-time collaborative reviews with the engineer of record and rebar detailer.

By reviewing and resolving shop drawing issues in a live session rather than passing PDFs back and forth, the team cut the submittal review cycle by more than 33% — compressing a 25-to-30-workday process into a 10-to-12-day window. That’s up to 10 days of schedule recovery per review cycle, on a project where every day had a dollar figure attached to it.

The results at Balfour Beatty’s DFW Airport renovation tell a similar story: $5 million in project savings attributed to centralizing documents and giving field teams real-time access to the information they needed, when they needed it. The savings didn’t come from a technology initiative; they came from fixing how information moved through the project.

Those aren’t outliers. They’re what Bluebeam sees when firms close the gap between having digital tools and ultimately running digital workflows. Among the 27% of construction firms currently using AI tools, 68% report saving at least $50,000 on recent projects, and 46% have saved 500-1,000 hours by applying AI to scheduling, planning and document analysis, according to the AEC Technology Outlook 2026.

What the firms getting these results have in common isn’t a particular software stack. It’s a single source of truth for project documents, accessible to every stakeholder in real time. It’s markups that are tracked, versioned and auditable — not living in email attachments. It’s RFI and submittal workflows that move in hours, not days. It’s a closeout process that doesn’t require assembling a package from five different places at the end of a job.

Bluebeam is built specifically for this kind of work — document-based collaboration that spans disciplines, formats and project phases without requiring firms to overhaul their entire tech stack. Bluebeam Max brings together markup, collaboration and project management in a single platform built for AEC workflows from design through closeout. Bluebeam’s customer stories offer a closer look at what these workflows produce in practice across firms of every size and type.

The Question Worth Asking

There’s no line item on a job cost report for “time spent looking for the right drawing.” There’s no budget category for “rework caused by working off the wrong version.” These costs are real, recurring and largely invisible — which is exactly why most firms haven’t done the math.

The math, when you do it, is uncomfortable. Hundreds of thousands of dollars per project in RFI management alone. Five percent of project value in rework, half of it caused by bad data. More than 14 hours a week per worker spent on things that aren’t building anything. Across a firm’s project portfolio, those numbers stop looking like friction and start looking like a structural problem.

The firms winning in this market — on thinner margins, with tighter crews — haven’t found ways to absorb those costs. They’ve found ways to stop incurring them.

If your team is working harder than the project warrants, the answer might be in how your documents are — or aren’t — moving. Bluebeam’s Document Management for Construction 2026 Guide is a good place to start that conversation.

See what a clean document workflow does on a live job.

The New York Times says America's infrastructure is stuck in permitting hell — and they're right. Yet they're missing half the story.

In January, a corroded section of the Potomac Interceptor sewer line burst in the Maryland suburbs of Washington, sending more than 240 million gallons of raw sewage toward the river — one of the largest such spills in U.S. history.

D.C. Water had wanted to reinforce that stretch of pipe for years, but the federal environmental review it needed dragged on well past a one-year deadline set in 2020, as a Washington Post investigation later documented. The pipe burst before the review was finished.

This spring, the New York Times Editorial Board used that story to make a case for permitting reform. The editors called for centralized oversight of transmission lines, binding timelines for environmental reviews and a congressional deal that speeds up infrastructure approvals without gutting environmental protections.

All good ideas. All politically hard.

All likely to take years.

Still, here’s what the Times missed: even if Congress passed permitting reform tomorrow, most public agencies would still be drowning.

Because the bottleneck is an operational problem that extends beyond what any regulation can accomplish.

I spent four years at the Office of Management and Budget watching federal agencies struggle with permitting timelines. Before that, I spent six years as an economist at the Bureau of Labor Statistics, building the data systems that agencies rely on to track what’s happening. I know what operational data looks like when it’s working and what it looks like when it isn’t.

At OMB, the delay was rarely the environmental analysis. Instead, it was version confusion, siloed reviews and comment reconciliation that nobody had ever properly resourced. That’s operational debt, and it accumulates quietly for years until a sewage line bursts. The good news is it doesn’t require an act of Congress to fix, just someone with the authority to look at the workflow honestly and decide that the status quo is no longer acceptable.

Federal environmental impact statements take an average of 3.8 years from start to finish. The Council on Environmental Quality’s own data shows that the gap between completing a final environmental review and issuing a decision averages 5.3 months — more than five times the 30-day regulatory minimum.

CEQ attributes that gap to “factors other than regulatory requirements.” In other words: administrative drag, not the environmental analysis itself.

We at Bluebeam work with hundreds of public agencies, and we’ve seen what happens when they stop doing the stupidest parts of their job. The results aren’t incremental.

Detroit went from issuing 3,000 permits a year to 7,500 — a 150% jump. Pleasanton, Calif., quadrupled per-reviewer capacity. Chicago’s Department of Transportation saved $24 million in 2022 by fixing utility coordination workflow.

What permitting looks like

Start in Las Vegas, 2018. The city handles more than 15,000 plan reviews a year. Before digital transformation, a customer walked in with two or three rolls of plans. A technician created a project number, manually stamped it on the plans and added a physical tag for tracking. Plans got checked into the system and stored in an “active” repository.

When a plans examiner was ready to review, they emailed the administrative staff with the plan number. The examiner physically walked to the repository. Staff retrieved the plans and logged them out. The examiner took the plans back to their desk, marked them up and returned them. Staff checked the plans back in, stored them again and waited for the next reviewer.

“Typically, we would have at least three to four different departments reviewing the plan and following this process,” Yolanda Palomo, process review coordinator for the city of Las Vegas, told Bluebeam.

That’s not 1985. That’s 2018.

Now zoom out. Seattle, same year. The city’s 430-person building department permits about $4 billion in construction annually.

Their review process didn’t use paper plans — but it wasn’t much better. Reviewers opened a submitted plan, then opened a separate text file to write corrections. Every comment went into that text file. When finished, an automated email sent the text file as an attachment. The applicant had to cross-reference the two documents to figure out what needed fixing.

It was siloed. Two digital documents that had to be manually reconciled. Version confusion was constant.

South Carolina, 2014. The state Department of Transportation launched a design-build team to accelerate infrastructure delivery. Yet their review workflow was killing that speed advantage. Reviewers submitted individual comments on separate forms sent via email. No centralized markup. No way to see what other reviewers had said.

“It was essentially like a relay race, where the baton is passed from the designer to the contractor,” Brooks Bickley, assistant program manager with the South Carolina Department of Transportation, told Bluebeam.

Where the time goes

When the Council on Environmental Quality publishes data showing environmental reviews averaging 4.5 years between 2010 and 2018, what does that time consist of?

A lot of it isn’t analysis, so much as coordination. CEQ’s own E-NEPA Report to Congress lays this out: agencies maintain “isolated, non-interoperable software systems.” Applicants submit the same data to multiple agencies. There are no common data standards; the public uses multiple platforms to track a single project.

Translation: agencies are spending months reconciling comments from different reviewers, chasing down the person who has the one marked-up copy, restarting review cycles because someone was working off version 2.3 when version 2.5 was current.

An Oregon Department of Transportation study of 12 highway projects found the strongest statistical correlation wasn’t between project complexity and timeline, but between the number of comment letters from state and federal agencies and the time to get from draft to final review.

More agencies commenting meant more time reconciling conflicting feedback, not necessarily more time analyzing environmental impacts.

A Federal Highway Administration survey of 89 long environmental reviews found the top delay drivers were lack of funding (18%), local controversy (16%), low priority (15%) and complex projects (13%).

Staffing and communication problems showed up in 42% of projects. These are workflow problems.

North Carolina saw this firsthand. Before implementing electronic plan review, the state’s multi-discipline reviews took weeks. After digitizing, North Carolina measured a 39% increase in productivity, not because they hired more staff or cut corners on compliance, but because they stopped losing time to coordination friction.

Las Vegas saw the same thing. Under the old paper system, plans could only be reviewed one discipline at a time — a week or more per discipline, across at least five departments. Printed mylars then had to be routed to five utility companies for final signatures, a process that took up to six weeks.

Then COVID hit.

The fix nobody’s talking about

March 2020. Every public agency in the country goes remote overnight. In most places, that would have been a disaster. Las Vegas, however, like the culture of the city itself, didn’t miss a beat.

“From my perspective, I don’t think we had any downtime due to COVID-19, other than the time that we waited to get laptops,” one city official told Bluebeam at the time.

Zero downtime, during a pandemic, for a department handling more than 15,000 plan reviews a year.

The city had replaced paper plans with digital files. Sequential review with concurrent review — multiple disciplines marking up the same plan at the same time. Physical repositories with cloud storage. Email attachments with real-time collaboration.

The regulatory requirements didn’t change. Las Vegas was still doing plan review, still checking compliance, still coordinating across departments. They just stopped doing it stupidly.

The results: eight-step paper process cut to four steps; $600,000 saved annually; reviews that used to take weeks now take days.

South Carolina cut design review time by 50%.

Detroit’s Buildings, Safety Engineering and Environmental Department went from issuing 3,000 permits a year to 7,500, supporting roughly $5 billion in development in 2023. Chief Building Official James Foster told Government Technology: “I can’t imagine how we would have been able to handle all of this if plan review were still on paper.”

Pleasanton’s Building Division saw per-reviewer plan checks go from 25 to 30 per month to roughly 100, nearly quadrupling capacity. Chief Building Official Robert Queirolo: “A plan check that might have taken six hours the old-fashioned way now takes a few hours.”

Chicago’s Department of Transportation implemented better utility coordination workflow and saved $24 million in 2022. They cut underground utility hits from the national average of 1.67 per 1,000 to 0.49.

Seattle ditched the separate text-file approach and moved to inline markup. In the first six months of 2022, the city approved 20% more complex construction permits than the previous six months. “The quality of communications was so high in our new system that we’re doing more volume — we are getting to ‘approved’ faster,” one city official told Bluebeam at the time.

What this means for infrastructure

The TransWest Express transmission line took 18 years to win final approval — not because anybody opposed clean energy, but because coordinating across jurisdictions, agencies and landowners is a nightmare.

That’s the same workflow problem Las Vegas had. The same coordination friction South Carolina faced. The same version confusion Seattle dealt with.

Policy reform matters. The SPEED Act, which passed the House in December 2025 and now sits before the Senate Environment and Public Works Committee, would streamline NEPA timelines and limit litigation windows. That would help.

But if your review process is still running on email attachments and paper round-trips, all the policy reform in the world won’t save you. You’ll just be doing bad workflow faster.

The emergency repair on the Potomac line is done and the water has cleared, but the cleanup has already run past its $20 million estimate — and the permanent fix still has to clear another round of environmental review, the same process that was too slow the first time.

Maybe Congress passes the SPEED Act. Maybe lawmakers broker a bipartisan deal. Maybe they don’t.

Yet while we wait, there are cities approving permits twice as fast because they stopped mailing PDFs and started marking them up in real time.

There are state departments of transportation cutting review cycles in half because reviewers can finally see each other’s comments.

There are public agencies that didn’t lose a single day during COVID because their workflow wasn’t dependent on paper.

It’s not sexy, and it won’t make the editorial page of the New York Times. But it’s the kind of infrastructure fix that doesn’t require a bill — just a willingness to look at how you’re really spending your time and admit that some of it is waste.

The permitting crisis is real. The Times is right about that.

But the fix isn’t just in Washington. Some of it is sitting in your own workflow, waiting for someone to finally admit it’s broken.

Parth Tikiwala is head of government affairs at Bluebeam and head of global public sector for the Nemetschek Group. He previously served as acting director of technology modernization and data at the U.S. Office of Management and Budget, Executive Office of the President.

Your agency’s biggest delay might be fixable right now.

Construction Ready has trained and placed thousands of workers since 1998. Here's how the pipeline gets built.

The skilled labor shortage doesn’t just keep contractors up at night. It keeps the whole industry honest. Every tool built for the jobsite depends on one thing: people who know how to use them. When the industry can’t find those people, everyone loses — the GC, the sub, the software company, the owner waiting on a building that isn’t coming.

That’s the context for what Construction Ready is doing in Georgia. And it’s worth paying attention to.

Scott Shelar grew up tagging along behind his grandfather — a small residential developer in Florida who built houses with his hands. But this was the 1980s, and the message to young people was loud and clear: Go to college.

So Shelar did. He wasn’t unusual. A whole generation of potential tradespeople got pushed in the same direction. The construction workforce has been paying the tab ever since.

Now Shelar is president and CEO of Construction Ready, a Georgia-based nonprofit working to close that gap since 1998 — when he first joined the organization. In January, Associated Builders and Contractors estimated the industry would need 349,000 new workers in 2026 alone to meet demand and 456,000 new workers in 2027. In Georgia, the annual shortfall runs about 10,000 workers. In 2024, Construction Ready brought more than 2,500 of them in.

“We’re having a 25% impact on the shortage we have in the state,” Shelar said. “It’s very measurable, and it’s very significant.”

Knocking down the door

The shortage isn’t just a contractor’s problem. It’s a people problem — generations of workers who were never shown a clear path into the trades, never told it was a real option, never handed the gear and credentials to walk onto a jobsite and get started. Nobody pulled them aside and said: This is a career. A good one. And here’s how you get in.

“We’ve really done a disservice to generations of young people by not lifting up those opportunities and giving them a real clear pathway and direction to pursue those opportunities,” Shelar said.

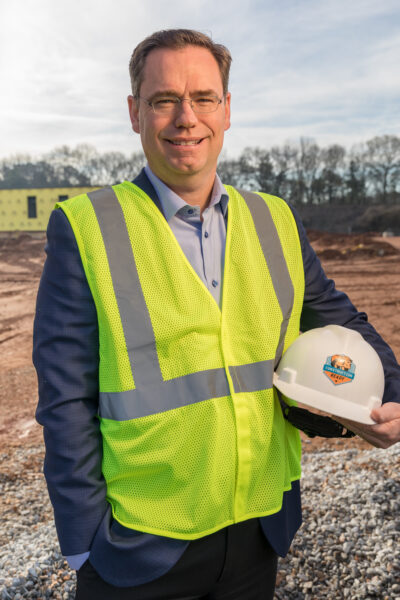
Scott Shelar, president and CEO of Construction Ready, at a construction site. Under Shelar, the Georgia nonprofit brought in more than 2,500 workers in 2024 — about 25% of the state’s annual shortfall. “It’s very measurable,” he says, “and it’s very significant.”

Construction Ready’s adult program attacks that problem directly. No tuition or prerequisites. Four weeks, 160 hours. Participants learn how to use power tools, how to read blueprints — and the stuff that matters just as much on a real jobsite: showing up on time, staying drug-free, understanding what employers need from someone on day one. Graduates walk out with OSHA 10-Hour certification, first-aid credentials and the tools and safety gear to start work immediately. Then Construction Ready runs a hiring fair with a 96% placement rate.

“The whole idea of the training is to knock down as many barriers as we can for a person wanting to get into our industry,” Shelar said.

That’s not a mission statement. That’s a design principle. The program is engineered around every friction point that typically stops someone from getting a foot in the door — cost, credentials, connections, gear. Remove enough of them, and people walk through.

Building the pipeline from the ground up

The adult program is the fast lane. The longer game is happening in schools.

Construction Ready supports more than 200 high school construction programs across Georgia, reaching more than 20,000 students. Carpentry, electrical, masonry, plumbing, architectural drafting, heavy equipment operation. Shelar calls it what it is: a talent pipeline. Not a feel-good initiative. Not a PR play.

A pipeline.

Still, pipelines need pressure to work. Shelar figured out early that one of the biggest leaks in the system was teacher retention. A skilled trades instructor can make considerably more money going back to industry. The good ones know it — and eventually, a lot of them go. So Construction Ready built a counteroffer: bonus checks of up to $10,000 for teachers, based on workforce impact — how many seniors they placed in the industry, how connected they are with local construction companies. Last year, the organization paid out more than $300,000 in bonuses across Georgia.

Trainees during a session of Construction Ready’s adult program. The free, four-week course — 160 hours, no tuition or prerequisites — pairs power-tool and blueprint instruction with job-readiness basics, then feeds a hiring fair with a 96% placement rate.

“To keep these good teachers in the classroom and not go back to industry, we figured out one of the key things is just more cash,” Shelar said.

No sugarcoating. That’s what works.

The pipeline now starts even earlier — middle school programs, elementary school visits, dedicated full-time construction teachers in some Georgia schools. The logic is dead simple: if you want someone choosing the trades at 18, you need them curious at 10. You need them to have touched a saw, read a plan, felt what it’s like to build something real — before anyone tells them it’s not for them.

“We have to start early,” Shelar said. “We have to start planting those seeds at a young age.”

The work ahead

Construction Ready runs on a mix of philanthropic funding, support from construction companies, and local, state and federal dollars. It has expanded into Florida. The challenges ahead are real — an aging skilled workforce, the constant pressure to scale, the grinding, daily work of convincing the next generation that a career built with your hands is worth choosing.

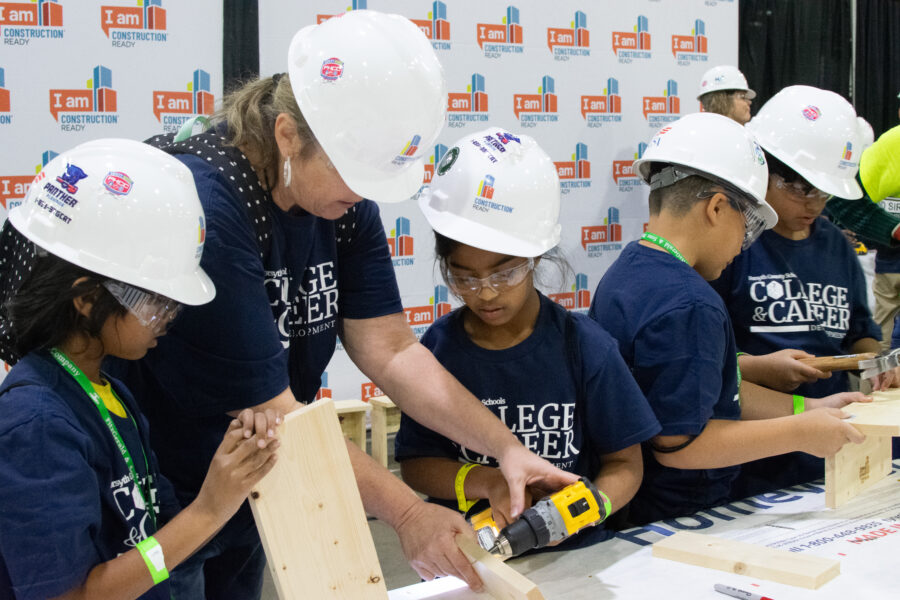
Young students try their hands at power tools at a Construction Ready event. The nonprofit’s pipeline now starts early — middle school programs, elementary school visits — on a simple logic: kids need to touch a saw and read a plan before anyone tells them the trades aren’t for them.

Shelar has been at this long enough to know what it means when it works — when someone finds a trade that clicks, gets placed, builds a life.

“Finding a career that you love is so important in life; we spend so much time working,” he said. “I love that we’re able to help people find a career that they love, a career where they can make a great living.”

That’s the whole point. Not just for Construction Ready, but for everyone who depends on a skilled, ready workforce to get the work done — the work that ultimately gets done, by actual people, on actual jobsites.

See why crews trust Bluebeam to keep the work moving.

Germany's most prosperous mid-size city is replacing a failing bridge, finishing a years-late train and staring down a housing gap that just keeps widening. The math works fine for everyone who already owns something.

The Theodor-Heuss-Brücke has been carrying Düsseldorf across the Rhine since 1957. As of Feb. 1, 2026, it cannot legally carry a vehicle heavier than 3.5 metric tons — barely a loaded cargo van.

The city council voted in July 2025 to replace it. €37 million in emergency stabilization buys time; planning takes years; construction won’t finish this decade. Heavy freight reroutes around it — and the IHK Düsseldorf has noted, bluntly, that the alternative crossings are weight-restricted too. There aren’t a lot of options left for anything heavy.

This is what building in Düsseldorf looks like in 2026. Major surgery on a city that’s still wide open for business. Not impossible. Just expensive — and the costs aren’t landing evenly.

The City That Works, on Infrastructure That Doesn’t

Düsseldorf is the capital of North Rhine-Westphalia: around 620,000 people, a banking hub, one of the world’s most important trade fair cities. Messe Düsseldorf generates an estimated €2.98 billion in nationwide sales and 27,700 jobs in a normal year, per the ifo Institute. More than a million trade visitors come through annually.

On paper, the problem isn’t construction; it’s a backlog. Office construction sat at roughly 140,000 square meters in early 2026 — well below long-term averages. Vacancy is around 1.28 million square meters at 12.7%, up roughly a point year over year. Hybrid work hollowed out conventional demand. What’s leasing is leasing less, in better buildings, with better energy ratings. Everyone else is waiting.

Six Years to Build a Train to the Airport

The U81 Stadtbahn was supposed to link the rail network to the airport and Messe grounds in time for UEFA Euro 2024. Five matches were played at the Düsseldorf Arena that summer. Hundreds of thousands of visitors came through. The U81 wasn’t running.

Construction began in late 2019. Original budget: roughly €230 million. By December 2022 — pandemic, war in Ukraine, raw material spikes — it was €336.3 million, a 46% overrun. Then came the low voltage screwup.

In autumn 2024, the city found that the Niederspannungsanlage — the cable system for lighting, controls and displays — had been miscalculated. A second firm got pulled in. That single package became a chokepoint for up to 40 downstream work packages. By April 2025, the opening had slipped to Q2 2026. In January 2026, Rheinbahn CEO Annette Grabbe told the Rheinische Post it would open “by June 30 at the latest.” The technical board member who’d run the project, Michael Richarz, left the Rheinbahn effective May 19, 2025.

The engineering, for what it’s worth, is genuinely impressive. The Nordsternbrücke — a 441-meter, semi-integral steel truss bridge, incrementally launched over a live autobahn interchange across nine cycles — won the European Steel Bridge Award in 2024. The underground airport station, cut-and-cover beneath the arrivals level and designed to carry future buildings on top, is serious work.

What the U81 tells you isn’t that Düsseldorf can’t handle complexity. It’s that you budget for delay before you budget for concrete. The full system — eventually crossing the Rhine toward Neuss and Meerbusch (the crossing alone is pegged at €215–€275 million) and pushing east toward Ratingen — runs into the 2030s.

The Housing Math Nobody Has Fixed

Four is the number that explains Düsseldorf’s construction market — the consecutive years NRW building permits have declined. In 2024, NRW approved just 40,554 apartments, down 34% from 2021 and the lowest since 2012. Nationally, completions hit 251,900 — a 14% drop, the weakest output since 2010. The government’s target was 400,000. ZIA’s 2024 forecast put the shortfall at 600,000 units, on a trajectory to 830,000 by 2027.

Düsseldorf’s pressure is acute. BBSR’s housing-demand projections put new-build need for major cities at 45 apartments per 10,000 residents per year, with hot markets like Munich at 74. Düsseldorf sits in the higher-need cluster. The city’s 8,000-unit housing initiative through 2030, backed by a €140 million Impulsprogramm running through 2027, acknowledges the gap. It won’t close it.

New construction commands a steep premium. New-build asking rents run around €22 per square meter — about 45% above the city average. Oberkassel purchase prices sit around €6,600–€6,800 per square meter; Oberbilk closer to €3,900. And Düsseldorf condominium prices rose 8.9% year-over-year in Q2 2025 — fastest among Germany’s top seven, per Cushman & Wakefield. The people building those apartments mostly aren’t the people who can afford to live in them.

The Energy Retrofit Mandate Nobody Agreed On

Germany’s Gebäudeenergiegesetz — the Building Energy Act — is one of the most contested laws in recent German politics. The 2023 version mandating heat-pump installation triggered a backlash that gutted the governing coalition’s standing well before it finally collapsed over the federal budget fight in late 2024. What survived still pushes decarbonization, just slower. The CDU/CSU–SPD coalition’s February 2026 Eckpunktepapier proposes scrapping the core requirements — but as of late April 2026, the bill is stuck in cabinet dispute. The existing law stands.

On the ground, retrofit is real construction work. KfW covers up to 70% of heat-pump installation costs for private homeowners. Germany sold 299,000 heat pumps in 2025, up 55% year over year — the first year they were roughly half of all heating appliance sales, though BWP itself notes the rebound partly reflects dealers clearing 2023 inventory rather than pure demand growth. National installer backlogs eased through 2025; specialized HVAC capacity is still tight.

Düsseldorf’s Wärmeplan — the mandated heat-transition road map — is scheduled to go to council May 7, 2026 (provisional). Today, 92% of the city’s heat is fossil. The municipal target is climate neutrality by 2035. In the Altbau stock that defines the inner city, getting from here to there means external insulation that often won’t fly on heritage facades, internal insulation that eats floor area, and heat-pump retrofits that routinely double in scope once the walls open up. The contractors who do this well are booked.

Labor Is the Binding Constraint

Across housing, office renovation, infrastructure and energy retrofit, the constraint is the same. IW Köln projects a nationwide skilled worker shortfall of 768,000 by 2028 — up nearly 60% from 2024’s 487,000 gap. Around 62% of Tiefbau firms — civil engineering and underground construction — can’t fill the roles they have. That’s the highest rate of any subsector. In a market defined by exactly that work, the number matters.

New apprenticeship contracts in construction ran well below the retirement rate in 2024. Roughly 40% don’t finish. The average construction worker exits active employment at 58, and one in three pension recipients in the sector draws a disability pension. The physical reality of the job makes this structural, not cyclical.

Germany’s €500 billion infrastructure Sondervermögen is starting to flow, with NRW set to receive roughly €21.1 billion. That money is chasing the same constrained labor pool. More funding without more workers doesn’t build faster. IW Köln warned in early 2026 that the skills gap could brake the entire investment impulse.

Why Düsseldorf Is Worth Watching Anyway

The case for Düsseldorf isn’t that it’s solved any of this. The bridge is failing. The train is late. The housing gap is widening. The case is that Düsseldorf is doing something harder than building in a city with room to grow: replacing major pieces of a working city’s infrastructure in real time. That’s the job facing every western European city that built its bones in the postwar boom and is now watching them age out at once.

The U81’s Rhine crossing — planning starting now, construction around 2030 — will tie Heerdt and Lörick to the transit spine for the first time. Developers who positioned in those corridors made a smart call. The Theodor-Heuss-Brücke replacement builds in a structural provision for later rail integration even though the current plan doesn’t fund it. Optionality on something the city will use for 60 years.

Policy is moving too. Germany’s “Bau-Turbo” fast-track permitting, in force since October 30, 2025, cuts review timelines for densification and adaptive reuse. Modular construction is still about 5% of the residential market by unit count, but mainstream bank financing is normalizing. Unmet demand is the mother of method change.

Düsseldorf’s construction market in 2026 is under real pressure — from a city that’s genuinely growing, genuinely in demand and genuinely constrained. The math works fine for everyone who already owns something. The question is whether it can build fast enough for everyone else.

Still chasing drawings across emails and versions? Fix it.

Construction cost estimators rely on reference cost databases, digital takeoff software, professional estimation services and industry certification to produce accurate bids. Here are the essential resources for 2026, including how Bluebeam fits into the modern estimator’s toolkit.

This article was originally published in October 2021 and has been updated for 2026 with current tools, resources and industry context.

Construction cost estimation is the process of forecasting the total cost of a construction project before work begins. It covers materials, labor, equipment, subcontractor costs, overhead and contingency, and it is the foundation of every competitive bid. A miscalculation at this stage does not stay contained but compounds through procurement, scheduling and contract terms, and it can turn a profitable job into a loss before the first shovel breaks ground.

Estimators in 2026 draw on four categories of resources: reference cost databases, digital takeoff and estimation software, external estimation services and professional development and certification. The right mix depends on project type, company size and market. Here is what each category looks like and what to look for.

Reference Cost Databases

Accurate estimation starts with accurate cost data. Unit costs for materials and labor vary by region, trade and market conditions, and experienced estimators know better than to rely on memory or outdated figures. Reference cost databases provide current, verified benchmarks that anchor the estimate.

RSMeans

RSMeans, published by Gordian, is the most widely used construction cost database in the United States and the recognized standard for public-sector procurement, insurance valuations and independent cost verification. Updated annually, RSMeans provides unit cost data for thousands of line items across residential, commercial and industrial construction, organized by CSI division and adjusted for regional cost factors. It is available in print and through an online platform that allows estimators to build cost models and export data directly.

For estimators working on US projects, RSMeans is the baseline. For Australian market readers, the Rawlinsons Australian Construction Handbook serves the equivalent function and remains the standard reference for projects there.

Regional and Trade-Specific Cost Guides

Beyond national databases, many estimators rely on trade-specific guides: the AISC Steel Construction Manual for structural steel, NECA labor unit manuals for electrical, MCAA labor standards for mechanical. These provide the granular unit costs and labor productivity rates that generalist databases approximate. Specialty contractors in particular benefit from trade-specific data that reflects the actual conditions of their work.

Digital Takeoff and Estimation Software

The single highest-impact upgrade an estimator can make is moving from paper-based or manual digital processes to purpose-built takeoff software. The difference is not incremental — it is categorical. Manual processes introduce scale errors, transcription mistakes and version drift. Digital tools eliminate entire categories of error at the source.

Bluebeam Revu

Bluebeam Revu is the industry’s leading PDF-based estimation platform, used by more than 4 million AEC professionals worldwide. Estimators use Revu to perform quantity takeoffs directly on PDF drawings, with tools including automatic scale calibration (which enforces correct scale on every page before a measurement is taken), Dynamic Fill for complex area measurements, VisualSearch for automated symbol counting, and Quantity Link for live synchronization between PDF markups and Microsoft Excel spreadsheets.

The platform’s impact is well documented. Solid Earth Civil Constructors caught a $50,000 measurement error on its first project using Revu and has since more than tripled its bidding output. ClearTech Engineered Solutions, an Irish specialist contractor, won 50% more projects after implementing Revu for estimation. For most commercial, civil and specialty contractors, Revu functions as a complete estimation platform for the takeoff phase, with Quantity Link bridging the output to whatever costing platform the team uses downstream.

Looking ahead: Bluebeam Max, the new AI-powered premium plan, adds Smart Review for catching design issues before they become change orders, Smart Overlay for AI-precision revision detection across drawing phases, and Claude AI integration for querying drawings and markup data with natural language prompts. For estimation teams managing large or complex plan sets, these tools close the gap between drawing review and quantity takeoff.

Specialized Estimation Platforms

For teams that require dedicated cost-modeling beyond what a takeoff tool provides, platforms such as STACK, PlanSwift and Sage Estimating offer built-in cost assemblies, bid management and integration with project management systems. These are more common among general contractors managing multi-trade estimates and bid packages at scale. Many teams use Bluebeam for the takeoff phase and export the quantity data into one of these platforms for final pricing.

External Estimation Services

Not every firm has the in-house capacity to handle every type of estimate. Smaller teams, firms bidding outside their typical project type, and organizations responding to an unusually high volume of RFQs often turn to external estimation consultants. These are specialists who perform takeoffs, feasibility studies, full estimates and cost analyses on a project or retainer basis.

External estimators bring several advantages beyond capacity. They carry current market knowledge across multiple project types, they are not subject to the institutional biases that can affect in-house estimates, and they often have direct relationships with subcontractors and suppliers that inform their pricing. The tradeoff is cost and turnaround time. For high-value or technically complex bids where internal expertise is thin, the investment is typically justified.

The key is vetting for trade and project type alignment. A civil estimator and an MEP estimator are not interchangeable. Look for consultants with direct experience in your specific project category and ask for references from comparable projects.

Professional Development and Certification

Estimation is a skilled discipline, and formal training accelerates the learning curve for new estimators and fills gaps for experienced ones. The recognized certifications in the field provide both technical grounding and professional credibility.

Certified Professional Estimator (CPE)

The CPE designation, offered by the American Society of Professional Estimators (ASPE), is the most recognized credential for construction cost estimators in the US. It requires documented experience, a written examination and continuing education. ASPE also publishes the Standard Estimating Practice manual, which is a useful reference for estimating methodology regardless of whether a candidate pursues the credential.

Certified Cost Professional (CCP)

The CCP, offered by AACE International (the Association for the Advancement of Cost Engineering), is broader in scope and recognized across construction, engineering and project management. It is particularly valuable for estimators working on large capital projects, infrastructure and energy, where cost engineering and cost control functions overlap with traditional estimation.

RICS Quantity Surveying Credentials

For estimators working in international markets or on projects governed by UK and Commonwealth standards, the Royal Institution of Chartered Surveyors (RICS) credentials — particularly the AssocRICS and MRICS designations — are the recognized standard. Quantity surveyors with RICS credentials are the default for procurement, contract administration and cost management on most major UK, Australian and Middle Eastern construction projects.

Bluebeam University

Beyond formal credentialing, Bluebeam University offers training courses specifically on Revu’s estimation and takeoff workflows, including quantity takeoffs, Quantity Link and custom column setup. For estimators already using Revu, structured training on the platform’s estimation features consistently produces measurable improvements in speed and accuracy.

What Separates a Good Estimate from a Costly One

The resources above provide the infrastructure for good estimation. What they cannot replace is disciplined process. The most common estimation failures are not knowledge gaps; they are process failures: working from an outdated drawing set, miscalibrating scale on a single sheet and not catching it, saving takeoffs to a personal drive with no version control. These mistakes are preventable with structured workflows and the right tools.

As one analysis of common takeoff failures notes, one miscalibrated scale can introduce roughly 10% quantity error across an entire sheet — an error that compounds into the final bid and does not surface until the project is underway. Digital tools with automatic scale enforcement, version-controlled document management and live cost synchronization eliminate the conditions that produce these errors.

The estimator’s job has always been to convert uncertainty into a defensible number. The tools and resources above do not remove that uncertainty but give the estimator the best possible foundation for managing it.

Frequently Asked Questions

What is construction cost estimation?

Construction cost estimation is the process of forecasting the total cost of a construction project, including materials, labor, equipment, subcontractor costs, overhead and contingency. Estimators use drawings, specifications, historical data, reference cost databases and digital tools to produce cost projections before bidding or budgeting. The estimate determines whether a project is financially viable and forms the basis of the contractor’s bid.

What software do construction cost estimators use?

Construction estimators commonly use Bluebeam Revu for digital quantity takeoffs directly on PDF drawings, with Quantity Link for live Excel integration. Other tools in the estimator’s stack include RSMeans for cost data, STACK or PlanSwift for bid assembly, and Procore or Autodesk Construction Cloud for project management integration. The specific combination depends on company size, project type and the estimator’s workflow.

What is the difference between a quantity takeoff and a cost estimate?

A quantity takeoff is the process of measuring and listing all materials, quantities and dimensions from construction drawings. A cost estimate takes those quantities and applies unit costs, labor rates, equipment costs, overhead and profit margins to forecast total project cost. The takeoff is an input to the estimate — inaccurate quantities produce inaccurate estimates regardless of how precisely the costs are applied.

How accurate are digital takeoffs compared to manual estimation?

Digital takeoffs are significantly more accurate than manual methods. Miscalibrated scale in a manual takeoff can introduce errors of 10% or more on a single sheet, and those errors compound across the estimate. Digital tools like Bluebeam enforce consistent scale on every page, automate measurement calculations and synchronize data directly with cost spreadsheets, eliminating several categories of error that affect manual processes.

What certifications do construction cost estimators need?

The most recognized US certifications are the Certified Professional Estimator (CPE) from the American Society of Professional Estimators and the Certified Cost Professional (CCP) from AACE International. For international markets and quantity surveying roles, RICS credentials (AssocRICS and MRICS) are the standard. Requirements and recognition vary by market, project type and employer.

What reference databases do construction estimators use?

RSMeans (published by Gordian) is the most widely used cost database in the United States, covering thousands of line items across residential, commercial and industrial construction with regional cost adjustments updated annually. Trade-specific references such as NECA labor unit manuals (electrical) and MCAA labor standards (mechanical) provide more granular data for specialty work. In Australia, the Rawlinsons Australian Construction Handbook serves the equivalent function.

How do external estimation consultants compare to in-house estimators?

External estimation consultants provide capacity relief, current market knowledge across project types and independence from institutional bias. They are most valuable for high-stakes bids outside the firm’s typical project type, for firms without dedicated estimation staff, or when responding to more RFQs than in-house capacity allows. The tradeoff is cost, turnaround time and less familiarity with the firm’s specific workflow and cost history.

See How Bluebeam Fits Into the Modern Estimation Workflow

Explore Bluebeam’s takeoff and estimation tools or start a free trial to see how Revu handles quantity takeoffs on your own drawings.

Related on BUILT:

• Bluebeam for Estimation: How Digital Takeoffs Reduce Errors, Save Time

• Bluebeam Quantity Link: A Deep Dive into Real-Time PDF-to-Excel Sync

• Quantity Takeoffs Are the Best Kept Secret in Bluebeam Revu

• How ClearTech Used Digital Estimation to Win 50% More Projects

• Your Takeoff Is Wrong. Here’s Why That Matters More Than You Think.

• The Power of Digitizing Quantity Takeoffs

The city isn’t choosing between growth and stewardship. It’s being forced to do both at once — on sinking ground, in a shrinking window, for people who can’t afford to live in what they’re building.

Across Mumbai’s construction sites, mornings begin the same way: the mukkadam is already doing math.

Not the kind they teach at IIT. The kind where you calculate how many workers you can move, how much material you can receive and how many minutes you have before the city wakes up and shuts the whole operation down. This scene — reconstructed from research on Mumbai’s construction economy — repeats itself thousands of times a day across the city.

The Bombay High Court says Mumbai’s citizens have a right to sleep. The traffic police say heavy goods vehicles are off the road by 7 a.m. The construction window — for one of the most complex urban rebuild programs on the planet — is maybe five hours long.

Somewhere under the mukkadam’s feet, a tunnel is being finished. Workers earning 615 rupees a day bored through coastal soft clay and 100-year-old colonial water mains to build a metro line that will move 1.6 million people.

Those workers won’t be riding it. They’ll pack up camp and follow the next job to the next neighborhood. The city will absorb what they built, appreciate around it and move on.

This is how Mumbai builds. Not by design. Because it couldn’t be stopped from becoming this.

Trapped on a Sinking Peninsula with Nowhere to Go

The city was built on seven islands stitched together over two centuries of British land reclamation. What you get is a 67-kilometer peninsula — Arabian Sea on one side, Thane Creek on the other — with roughly 22 million people on it and nowhere to expand.

The answer so far: go up. Go inward. Which sounds simple until you’re standing on ground that’s sinking 2 millimeters per year, mostly below the high-water mark, in a city where more than 60% of the population lives in flood-prone wards.

The grand vision is what officials call the “45- to 60-minute city” — knitting this impossible geography together with bridges, tunnels and metro lines fast enough that the whole thing holds. Whether the geology cooperates is a different question.

The Underground Bet That Actually Paid Off

The Aqua Line — Metro Line 3 — is 33.5 kilometers of fully underground metro connecting South Mumbai’s financial district to the northern hubs where the offices and airport are. Going elevated would have meant demolishing thousands of historic structures. So, they went deeper.

Originally budgeted at 23,136 crore rupees in 2011, the final cost reached roughly 37,000 crore rupees — a 60% overrun. It cut a 90-minute commute to 30. Property values near its 27 stations are up 10% to 40% by industry estimates. It is, straight up, an infrastructure achievement that deserves to be called that.

The part nobody talks about: the workers who built it can’t afford to live within 30 kilometers of it. That’s not a critique of the metro, but a fact about the city the metro was built to serve.

The $1 Billion Economy the City Wants to Tear Down

Dharavi sits in the heart of Mumbai — low-rise, dense, inadequate sanitation, fire risk in every lane. It is also, by most estimates, a $1 billion to $1.5 billion economy. Leather manufacturers, pottery hubs, recycling networks processing a substantial share of the city’s dry waste. Ground floors: workshops. Floors above: homes. Lanes between them: supply chains.

The Adani Group’s redevelopment project, valued at roughly 20,000 crore rupees in capital investment, would replace this with high-rise towers and formal commercial zones. Free apartments — 350 to 405 square feet — for eligible residents.

Activists and housing researchers warn that a large share of current residents — some advocacy groups put the figure as high as 75%, though methodologies vary — may not qualify for in-situ resettlement, meaning displacement to peripheral salt pan lands far from the economy they built their lives around. You can give someone a flat. You can’t give them back the economy they built in a place.

The Mukkadam System: Who Actually Builds This City

The people who build Mumbai come from elsewhere.

India’s construction sector is among the country’s largest employers, drawing heavily on interstate migrants from Bihar, Uttar Pradesh, Odisha and West Bengal.

They come via the mukkadam: a labor gang leader who is part recruiter, part advance lender, part site supervisor — and entirely a mechanism for relieving the owners of capital from any obligation to the people doing the actual work. No formal contracts. No social protection. Nothing guaranteed except the work and the wage.

The wage in 2025: roughly 615 rupees a day for skilled workers, 435 for unskilled, consistent with Maharashtra state wage schedules. A substantial share of these workers — surveys suggest a majority — live in informal settlements or camps near jobsites, in the same conditions they were brought to Mumbai to build people out of.

Malaria slide positivity among migrant construction workers has been recorded as high as 8.11% in Mumbai studies — workers sleeping near open excavation pits in waterlogged ground are, in the clinical language of public health, “potential baits” for mosquitoes. Fewer than one in five have received any formal skill training. They learn on the job. On Mumbai’s job.

The construction boom powering Mumbai’s luxury market is being built by workers sending money home to villages they can’t afford to leave — the most load-bearing part of the operation, with the fewest obligations attached to them.

The mukkadam system is not a bug in Mumbai’s construction economy. It is the construction economy. Everything else — the FSI regulations, the metro lines, the green building certifications — sits on top of it.

The Number Nobody Wants to Say Out Loud: 30 Centimeters

That’s the projected relative sea-level rise by 2050 — thermal expansion combined with 2 millimeters per year of local subsidence. Thirty centimeters sounds manageable. The problem is Mumbai’s drainage system — BRIMSTOWAD, a two-decade infrastructure project — runs on gravity. When the sea rises even slightly, high tides start blocking the outfalls. Rain falls. The tide pushes back. The water sits.

After the 2005 floods killed more than 1,000 people in a single day, official reviews called for dramatically expanded drainage capacity. The upgrades delivered fell short of those targets — a gap that remains contested in engineering and policy circles. Documented “desilting fraud” — drains billed as cleared but left silted — has compounded the shortfall.

Monsoon rainfall is projected to intensify significantly by 2050, with some studies pointing to increases of 30% or more in extreme rainfall events. Roughly 40% of Mumbai’s mangrove cover — the city’s natural storm buffer — is already gone. The city is certifying luxury towers with green ratings while the drainage underneath them drowns in a math problem that hasn’t been solved.

Why Every City That Comes After Mumbai Is Watching

Jakarta is abandoning its capital. Beijing expanded outward. Mumbai has no exit strategy — making it the most honest construction market in the world for cities that will face the same pressures, not because it’s getting it right, but because it has no choice except to try.

That version where it works — where the Aqua Line is Phase 1 of an affordable transit network, where Dharavi’s economy survives its own redevelopment, where the drains get fixed before 2050 — is possible. It requires deciding who Mumbai is being rebuilt for.

The current answer is: whoever can pay. That’s not an answer. It’s a delay.

See how teams keep projects moving when conditions fight back.

As Amazon’s copper deal shows, the biggest constraint on artificial intelligence isn’t computing power, but the slow, friction-filled systems required to build and power it.

When Amazon quietly agreed to buy copper from the first new U.S. mine to come online in more than a decade, the headline read like a niche supply chain story.

Another tech giant hedging risk. Another materials deal buried beneath flashier AI announcements.

But that’s not what this move really signals.

Amazon isn’t buying copper because it suddenly cares about mining. It’s buying copper because the infrastructure required to support artificial intelligence is colliding with physical limits — limits that software, capital and ambition can’t wish away.

Copper sits at the center of that collision. It’s essential to data centers, power distribution, transformers, substations and transmission lines. Every megawatt of new AI capacity brings massive amounts of metal, wiring and coordination with it.

And unlike chips or code, copper doesn’t scale on demand.

The deal itself won’t meaningfully satisfy Amazon’s needs. Even optimistic production estimates from the Arizona mine represent only a fraction of what a single hyperscale data center consumes.

That’s the point.

This isn’t about supply security in isolation, but about what happens when the digital economy starts outrunning the systems that make it possible to build, power and operate it.

Amazon’s copper purchase isn’t a bet on materials as much as it’s an admission that the AI boom is running headlong into the physical world, and that the bottleneck is no longer computing power but execution.

AI’s timing problem

Artificial intelligence moves fast because it can.

New models train in months. New chips deploy in quarters, and cloud capacity expands modularly as demand rises.

The physical systems that support it don’t.

This is the core mismatch shaping the future of AI infrastructure. Technology advances on roughly 18-month cycles. Infrastructure operates on timelines measured in years, often decades.

Transmission lines routinely take six to 10 years to permit and build. New mines, on the other hand, can take nearly 30 years in the United States from discovery to production. Grid interconnection approvals in high-demand regions now stretch well beyond five years.

That gap isn’t theoretical, either, but it’s already reshaping where — and whether — projects move forward.

A data center can be designed and built in under two years. The electrical infrastructure required to serve it, however, may arrive long after the facility is ready to switch on.

In some regions, developers are pouring concrete and ordering equipment without knowing when — or if — sufficient power will be available. Capital sits stranded while approvals crawl forward.

This is why Amazon’s copper deal matters — because it reflects a growing realization among hyperscalers that infrastructure risk now lives upstream of technology decisions. By the time a power line is approved or a new material source comes online, the AI workload it was meant to support may already be obsolete.

The physical world isn’t built to win that race.

Infrastructure systems were designed for steady, predictable growth — not exponential growth in demand driven by AI. As technological change accelerates, delays that once felt manageable now compound into strategic constraints.

Miss a window, and a project doesn’t just run late. It risks irrelevance.

Copper is the canary

Copper isn’t scarce because demand surprised the market. It’s scarce because the systems that produce it were never built to respond quickly and can’t be retrofitted overnight.

That’s what makes copper such a useful lens for understanding the broader infrastructure challenge facing AI.

It’s non-substitutable at scale and deeply embedded in power and data systems, and it’s required in quantities that only become obvious once projects are underway.

Modern AI data centers are especially copper-intensive. High-density computing power, liquid cooling and redundant power systems all push material needs higher. On average, an AI training data center requires roughly 47 metric tons of copper per megawatt of installed capacity.

Over a facility’s lifecycle, that figure climbs further.

Multiply that across hundreds of megawatts, and the demand curve steepens fast.

The problem is that copper supply doesn’t bend to price signals on useful timelines. New mines take decades to develop. In the U.S., the process can stretch close to 30 years. Globally, declining ore grades and rising technical complexity slow expansion even more.

The result is a structural gap.

Forecasts already point to a multimillion-ton shortfall by 2040, even under optimistic assumptions. That gap shows up in elevated prices, long procurement timelines and strategic behavior like Amazon’s decision to secure supply directly.

Still, copper itself isn’t the real story but the proxy.

Every system AI depends on shares the same traits: heavy upfront investment, long approval timelines, limited substitution options and high coordination complexity.

Power transformers. Switchgear. Transmission corridors. Cooling infrastructure.

When demand spikes, these systems don’t scale. They strain.

Seen through that lens, Amazon’s copper deal isn’t about cornering a market but about buying certainty in a world where physical inputs have become gating factors.

And once materials become gating factors, every inefficiency downstream matters more.

Even when supply exists, projects still stall

Material shortages and permitting delays are easy targets because they sit outside the jobsite. Yet even when approvals are secured and materials are available, projects still lose time — and a surprising amount of it.

The culprit: execution friction.

Across construction, rework accounts for an estimated 9% to 20% of total project costs. Nearly a third of work performed on active jobsites is spent correcting errors rather than moving forward.

These aren’t edge cases, either; they’re systemic.

Data center construction magnifies the problem. Mechanical, electrical and plumbing systems dominate cost and complexity. Tight tolerances leave little margin for error.

A single clash discovered in the field rather than on a drawing can trigger cascading delays. Crews stop. Equipment sits idle. Schedules unravel.

At the root of much of this rework is bad information: outdated drawings, conflicting markups, incomplete submittals and misaligned assumptions.

Individually, these issues seem manageable. Collectively, they drag the entire system down.

In an environment where AI workloads evolve every 18 months, losing weeks or months to coordination failures isn’t just inefficient.

It’s strategic risk.

When timelines slip, projects don’t simply cost more, but they miss windows and arrive late to markets that have already moved on.

The uncomfortable truth: the industry doesn’t just lack materials — it leaks time.

And as physical constraints tighten, that leakage becomes harder to absorb.

The grid is already telling us the truth

If there’s any doubt that physical constraints have overtaken digital ambition, the power grid has been making the case.

In the U.S., grid interconnection queues have swollen to nearly 2,600 gigawatts of proposed capacity — more than twice the country’s total installed power plant fleet.

The system isn’t just congested but overwhelmed.

For data center builders, that means years of uncertainty. Projects that are otherwise ready to move forward stall while studies drag on. Grid operators in some regions have paused new connection requests entirely just to process existing backlogs.

Capital is committed. Sites are secured. Construction may begin.

Power, however, remains a question mark.

Europe faces similar constraints, particularly in long-established data center hubs.

In Dublin, for example, Ireland’s grid operator effectively imposed a moratorium on new data center connections due to capacity limits, allowing projects only under strict conditions. Amsterdam has also faced grid congestion that has slowed or paused development, while in Frankfurt, demand for power is already exceeding available grid capacity.

Across the region, long grid connection timelines — sometimes stretching up to seven years — are increasingly shaping whether projects move forward at all. Connection timelines stretch seven to 10 years, far longer than the typical construction cycle of a modern data center.

These aren’t future warnings as much as they’re present constraints shaping real investment decisions today.

The grid isn’t signaling what might happen if AI grows unchecked. It’s showing what happens when physical systems are asked to move at digital speed — and can’t.

From paperwork to critical infrastructure

As AI infrastructure pushes against physical limits, one reality becomes harder to ignore: how projects are planned, coordinated and delivered now matters as much as the materials themselves.

For decades, drawings, markups and approvals were treated as administrative artifacts — necessary, but secondary to “real work” in the field.

In a world of compressed timelines and thin margins for error, construction information has now become critical infrastructure.

When teams lack clarity — when they’re working from outdated drawings, conflicting markups or incomplete approvals — friction compounds. Crews hesitate. Work stops and starts. Rework spreads.

What once might have been a minor delay becomes a schedule-breaking problem.

The companies that perform best in this environment won’t be the ones that simply secure more materials or chase faster hardware cycles.

They’ll be the ones that reduce uncertainty.

Fewer handoff errors. Fewer version conflicts. Faster alignment between design intent and field execution.

This isn’t about adopting new tools for their own sake, but about recognizing that coordination failures now carry outsized consequences.

When copper is scarce, power is constrained and approvals take years, there’s far less room to absorb mistakes.

As the physical economy becomes the limiting factor for digital growth, execution discipline becomes a competitive advantage.

The real risk to AI isn’t innovation … it’s friction

Amazon’s copper deal isn’t an outlier.

It’s an early signal.

As AI infrastructure expands, more companies will move upstream — securing materials, power and capacity not because they want to, but because uncertainty has become too costly to ignore.

This is what happens when digital growth collides with physical systems that can’t move fast enough.

The danger isn’t that AI development slows but that it becomes uneven. Large players with the capital to absorb delays or pre-buy supply will keep moving. Others will wait in interconnection queues, navigate multi-year approvals and watch windows close.

The gap won’t be technological. It will be infrastructural.

The next phase of the AI economy won’t be defined solely by faster models or more powerful chips, but by how quickly the physical world can respond — and how much waste we’re willing to tolerate along the way.

In that reality, the teams that succeed won’t just build more.

They’ll build with clarity, coordination and discipline, treating execution not as an afterthought, but as the infrastructure that makes everything else possible.

How does Bluebeam help reduce execution friction on complex infrastructure projects?

Bluebeam helps teams align around a single, trusted set of drawings and documents. By centralizing markups, measurements and revisions in real time, it reduces the version conflicts and information gaps that drive rework, delays and downstream coordination failures on high-stakes projects.

Why does construction information matter more as AI infrastructure timelines compress?

When material supply, power access and approvals are already constrained, there’s little tolerance for mistakes. Bluebeam treats drawings and approvals as operational infrastructure, helping teams surface issues earlier, coordinate faster and keep execution aligned with design intent as schedules tighten.

How does Bluebeam support data center and power-intensive builds?

Data centers concentrate complexity in electrical, mechanical and coordination-heavy scopes. Bluebeam enables detailed reviews, clash identification and field-to-office communication across those systems, helping teams catch problems digitally before they stall work in the field or strand capital.

Does Bluebeam replace other construction or project management platforms?

No. Bluebeam complements project management, BIM and ERP systems by strengthening the layer where most execution friction lives: drawings, documents and collaboration. It integrates into existing workflows, improving clarity and coordination without forcing teams to rebuild their tech stack.

What makes Bluebeam relevant as physical constraints become the bottleneck?

As materials, power and permitting become gating factors, the competitive edge shifts to execution discipline. Bluebeam helps teams waste less time, absorb less rework and move with greater certainty — turning coordination from an afterthought into an advantage.

Image created using generative AI.

Build faster when every drawing and decision actually lines up.

Featured Guides